Planning to purchase or renovate a home using an FHA 203(k) loan? Precision Remodeling provides professional residential renovation services designed to help homeowners complete qualifying improvement projects with quality workmanship and clear project coordination.
From kitchens and bathrooms to major home improvements, our team can help bring your renovation plans to life.
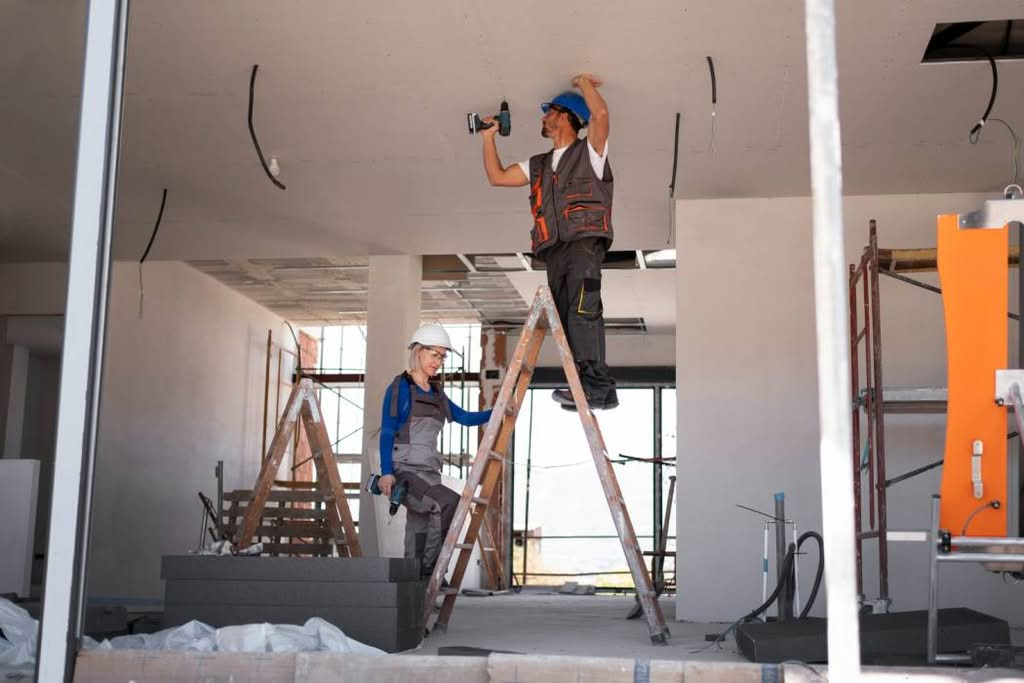
Residential Remodeling
Experienced Contractors
Detailed Project Planning
Quality Workmanship
Cabinetry, countertops, flooring, lighting, plumbing fixtures and complete kitchen renovations.
Showers, tubs, vanities, flooring, fixtures and complete bathroom improvements.
Flooring, drywall, painting, doors, trim and other interior improvements.
Siding, roofing, doors, windows and qualifying exterior repairs.
Residential improvements involving larger renovation scopes where permitted and approved.
Electrical, plumbing, HVAC and other essential property improvements.
Designed primarily for less extensive repairs and non-structural improvements.
Examples:
Designed for more extensive rehabilitation and projects that may include major or structural work.
Examples:
Share your renovation needs, property details and proposed scope of work.
We review the required improvements and prepare project information and estimates based on the proposed renovation.
Once financing and the renovation scope are approved, we coordinate construction according to the agreed project requirements.
Our team performs the residential renovation with attention to quality, communication and project completion.
Residential remodeling expertise
Detailed project estimates
Clear scope of work
Professional project coordination
Quality materials and workmanship
One team for multiple areas of your home
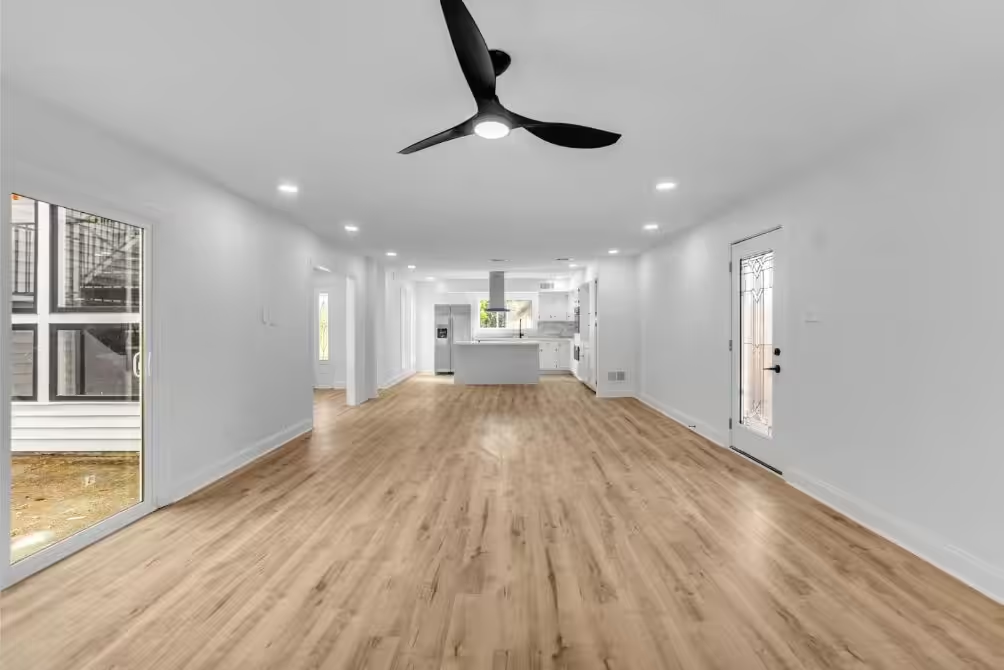
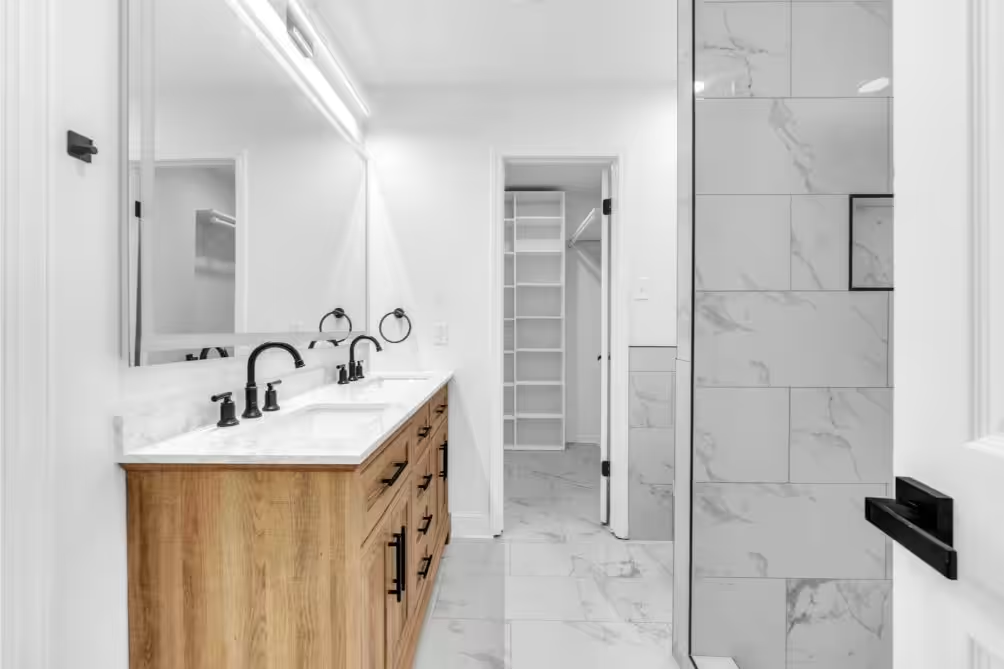
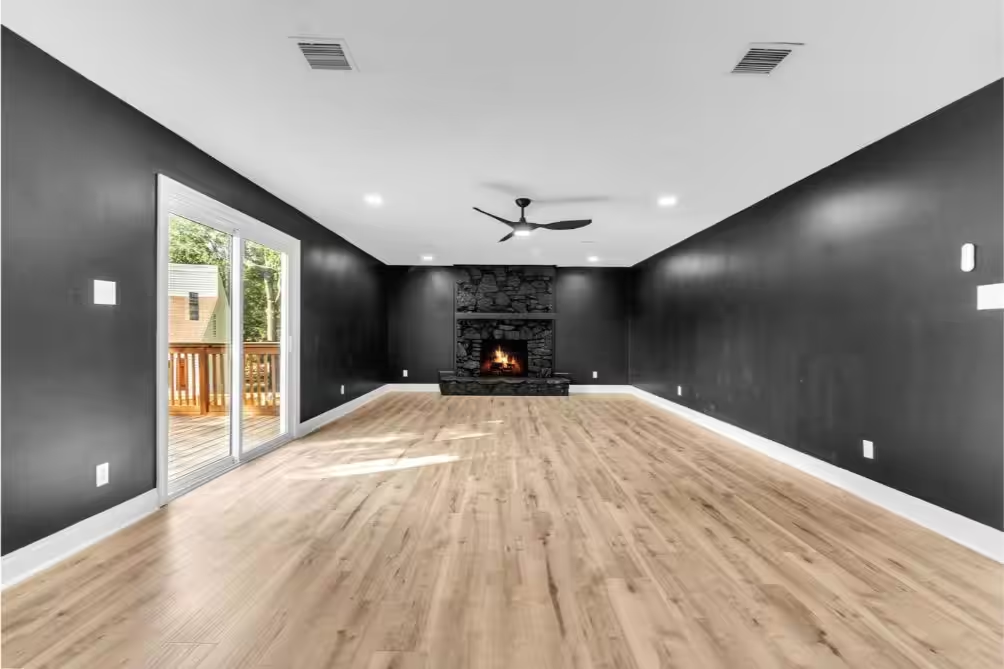
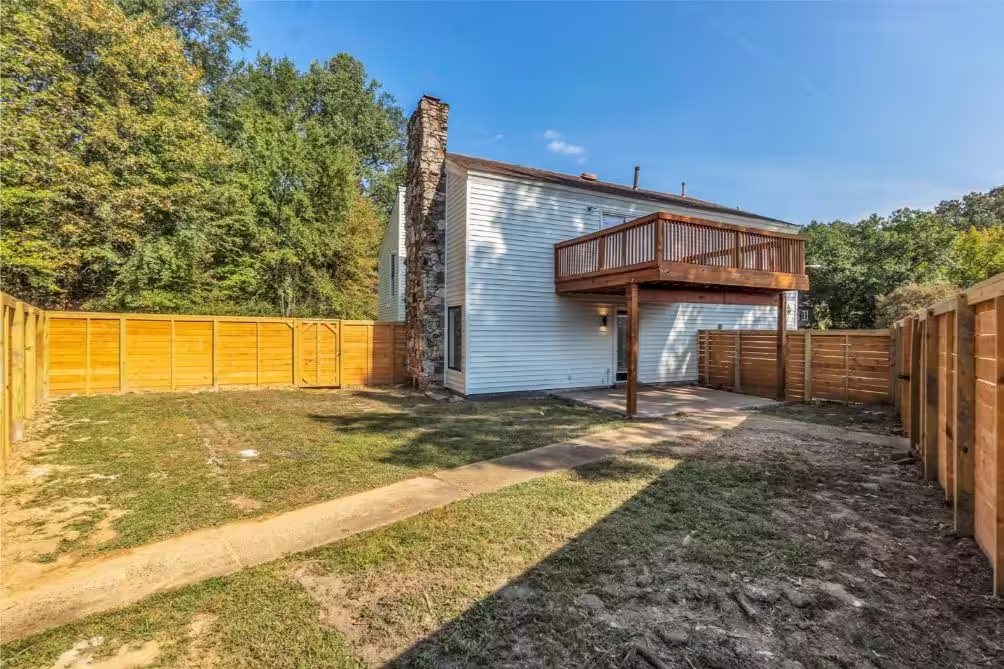
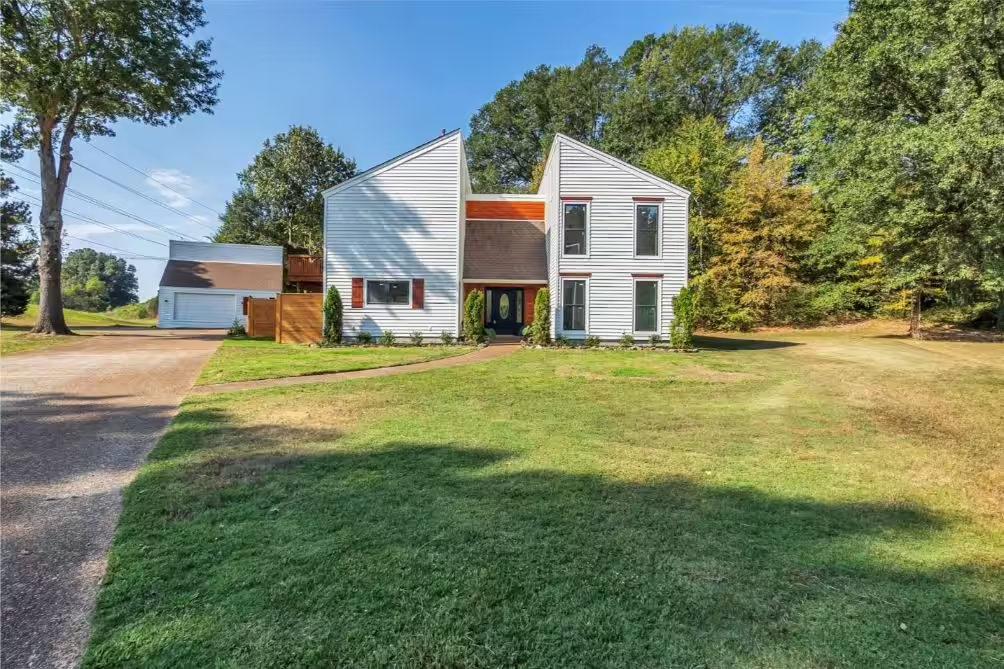
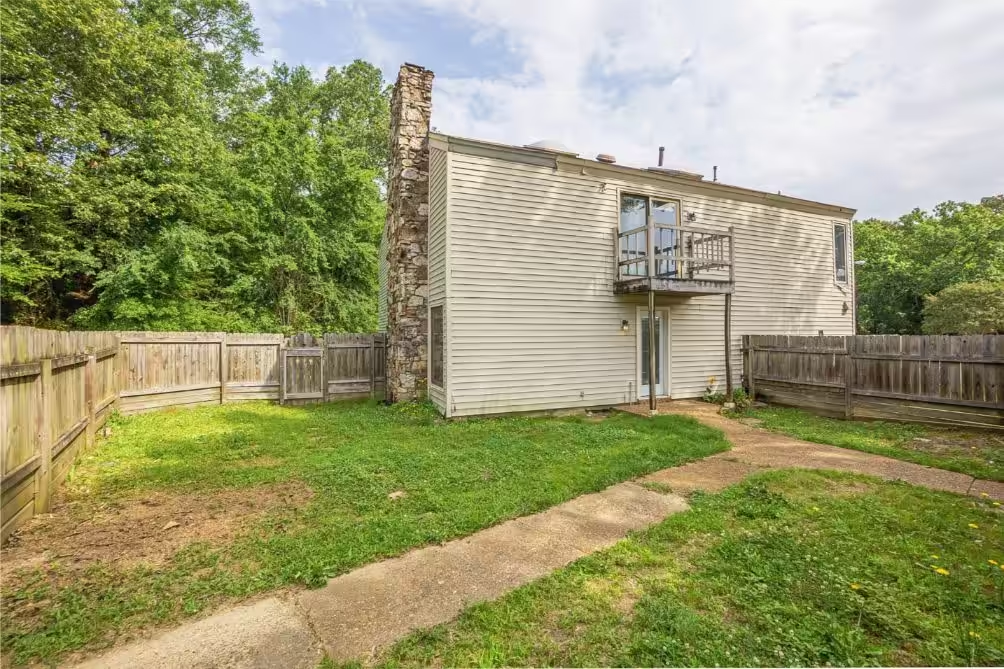
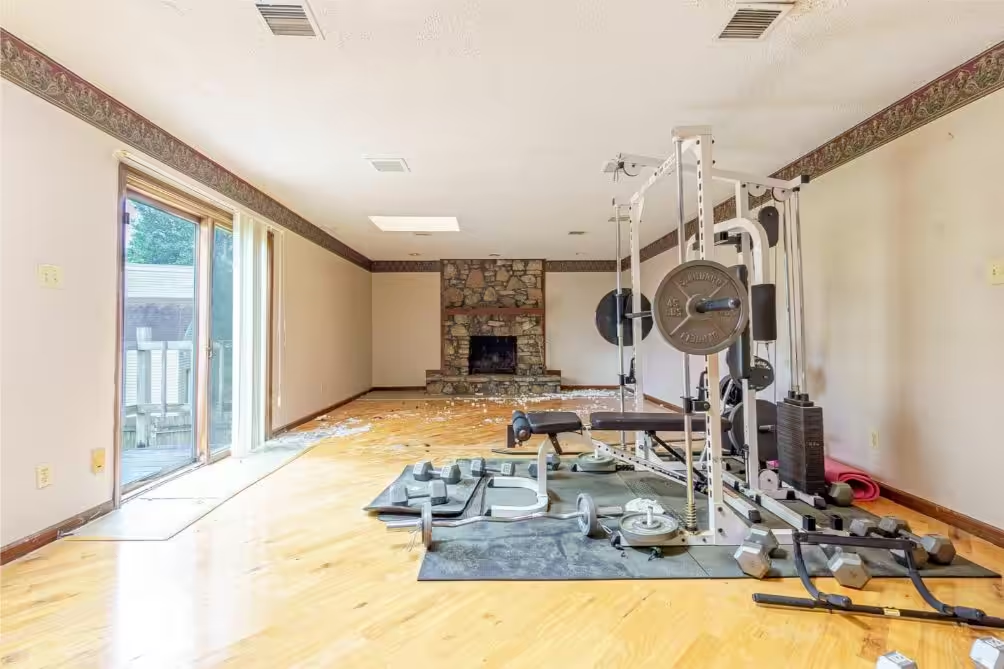
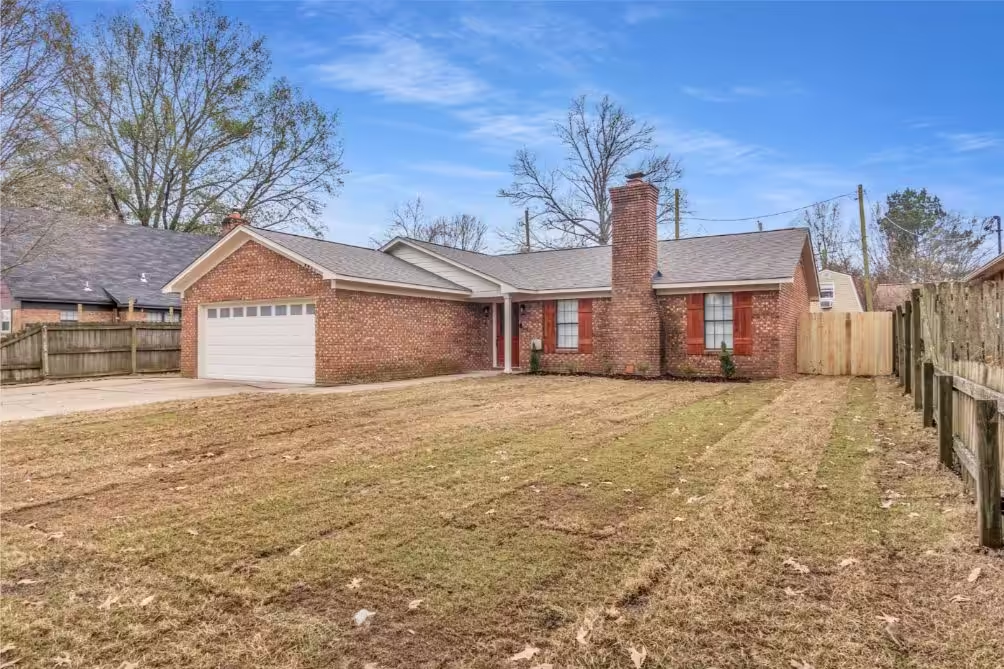
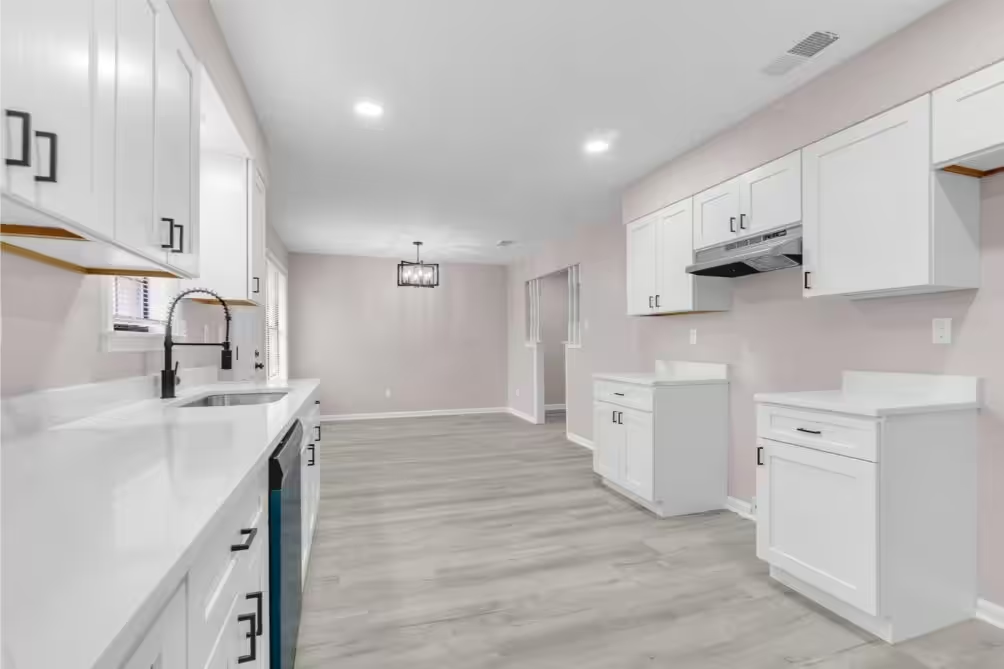
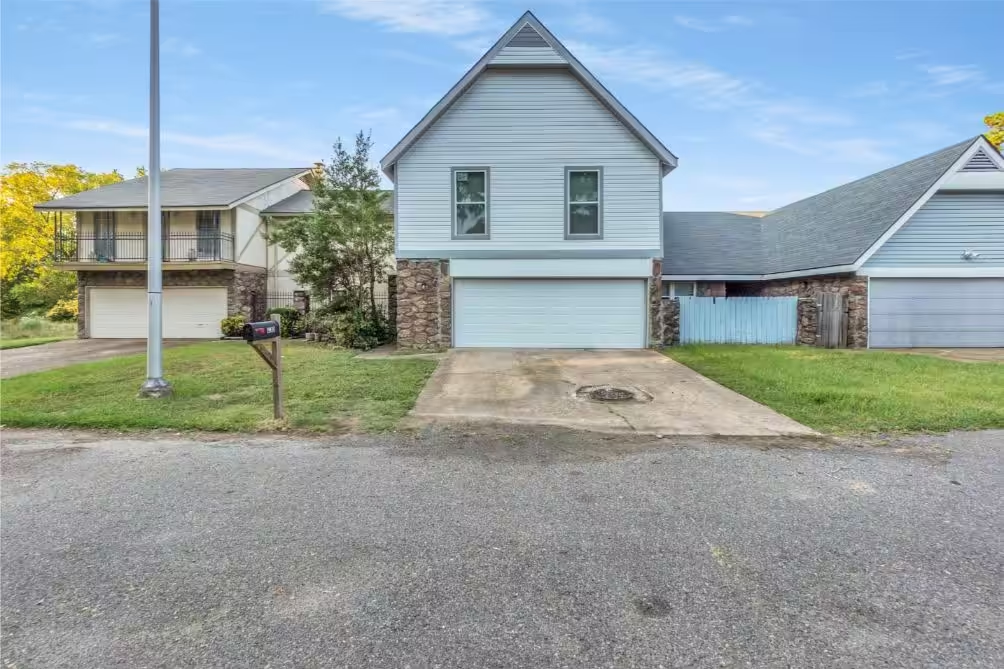
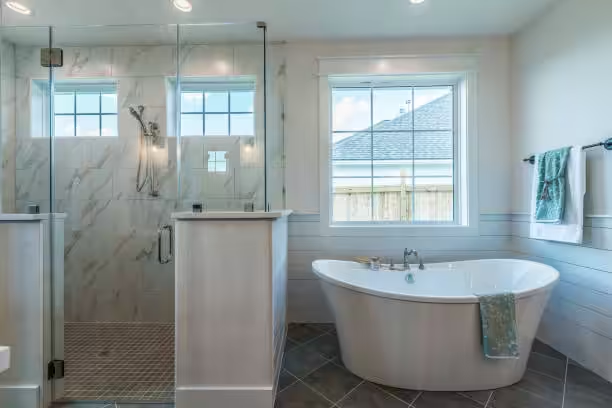
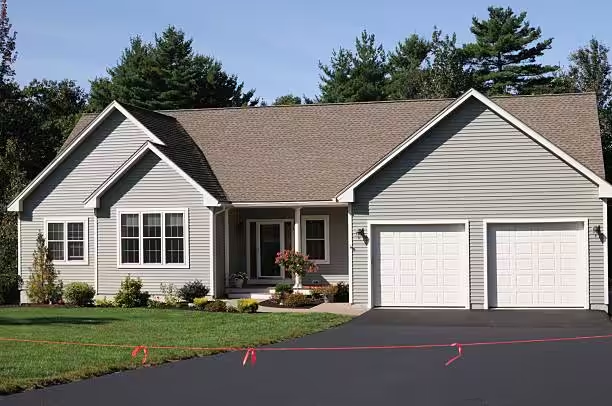
A house with good bones and outdated everything else can be a genuinely great deal, if you can afford both the purchase and the renovation. That’s exactly the gap an FHA 203(k) loan is built to close, and it’s exactly where the right FHA 203(k) contractor makes or breaks the whole project.
This page walks through what a 203(k) contractor actually is, how the loan process works alongside the renovation, and what separates a contractor who keeps your draws moving on schedule from one who quietly slows everything down.
A 203k contractor is a licensed general contractor who works within the specific requirements of the FHA 203(k) renovation loan program, a loan that lets homebuyers finance both the purchase price of a home and the cost of renovating it, rolled into a single mortgage. Unlike a typical remodeling project paid out of pocket, a 203(k) project is tied directly to loan draws, inspections, and paperwork requirements set by the lender and HUD.
This matters because the contractor isn’t just building, they’re also responsible for submitting accurate cost estimates, staying within approved scope, and completing work on the timeline the loan requires.
An FHA 203(k) loan wraps the purchase price and renovation cost into one mortgage, based on the home’s projected value after the work is complete, not its current, as-is condition. Funds for the renovation aren’t handed over all at once; they’re held in an escrow account and released in draws as work is completed and verified by inspection.
According to HUD’s official 203(k) program overview, this structure exists specifically to protect both the lender and the homeowner, ensuring renovation funds are actually spent on completing the approved work.
Not every 203(k) loan works the same way. The two main versions differ significantly in scope:
Knowing which category your project falls into shapes almost everything else, the paperwork required, the timeline, and which contractors are even eligible to bid the work.
There’s no single national “203k certification exam” the way there is for some trades, instead, being 203k certified in practice means a contractor understands the program’s specific requirements: how draws work, how to submit a compliant cost estimate (“specification of repairs”), and how to work alongside a HUD consultant when one is required. Many lenders also maintain an approved contractor list, and being on it typically requires proof of licensing, insurance, and sometimes prior 203(k) project experience.
A 203k general contractor who’s done this before will move your project through inspections and draws far more smoothly than one encountering the paperwork for the first time.
Before hiring any 203k contractor near me, confirm:
A 203k licensed contractor who can’t speak comfortably about draws, consultants, or HUD specifications probably hasn’t done many of these projects, and this isn’t the loan type to learn on.
Every step depends on the one before it moving smoothly, which is exactly why contractor experience with this specific process matters so much.
If you’re trying to finance your home renovation and don’t have significant cash reserves, a 203(k) loan is one of the more accessible paths, especially for buyers purchasing a home that needs work as a condition of financing at all, some lenders won’t approve a mortgage on a home in poor condition without a renovation plan attached. The process starts with your lender, not your contractor, but choosing a contractor experienced in this program early, even before your offer is accepted, can meaningfully speed up the rest of the process.
A few recurring issues tend to slow down or derail 203(k) projects:
Working with a fha 203k general contractor who’s navigated these issues before is the single biggest factor in avoiding them yourself.
The contractor you choose affects more than construction quality on a 203(k) project, they directly affect whether your draws release on time, whether your loan timeline holds, and whether inspections go smoothly. An inexperienced contractor can genuinely stall a project for weeks over paperwork issues that an experienced fha 203 k contractor would have avoided from the start.
Precision Remodeling has guided Memphis and Germantown homeowners through the 203(k) process for over a decade, working directly with lenders and consultants to keep draws, inspections, and construction moving together instead of against each other. If you want the full walkthrough of how to vet a contractor for this specific loan type, our in-depth FHA 203k Contractor Guide covers the vetting process in more detail.
If you’re comparing a 203k contractor near me or 203k general contractor near me, here’s what sets Precision Remodeling apart:
We provide fha 203k contractor services throughout:
Memphis, TN · Germantown, TN · Collierville, TN · Bartlett, TN · Eads, TN · Somerville, TN · Atoka, TN · Brighton, TN · Munford, TN · Millington, TN · Southaven, MS · Olive Branch, MS
Don’t see your city listed? Reach out directly, we cover a wider radius on request.
Q: What is an FHA 203(k) contractor?
A: A licensed general contractor experienced in working within the FHA 203(k) renovation loan program submitting compliant cost estimates, managing draw inspections, and completing work on the loan’s required timeline.
Q: How does an FHA 203(k) loan work?
A: It combines the home’s purchase price and renovation cost into a single mortgage, based on the projected after-renovation value. Renovation funds are held in escrow and released in draws as work is inspected and verified.
Q: What’s the difference between a Standard and Limited 203(k) loan?
A: A Limited 203(k) covers smaller, non-structural projects without a required consultant. A Standard 203(k) covers larger projects, including structural work, and requires a HUD-approved consultant.
Q: What makes a contractor “203k certified” or “203k licensed”?
A: There’s no single national certification exam, it typically means active general contractor licensing plus direct experience navigating 203(k) draws, inspections, and specification requirements. Many lenders also maintain their own approved contractor lists.
Q: How do I find a 203k contractor near me?
A: Confirm active licensing and insurance, ask specifically about their experience with 203(k) draws and inspections, and request a written estimate built to meet lender specification requirements.
Q: How can I finance my home renovation with a 203(k) loan?
A: The process starts with your lender, but choosing an experienced 203(k) contractor early, even before your home purchase closes, can help the entire process move more smoothly.
Q: What are common mistakes homeowners make with 203(k) projects?
A: Underestimating the timeline for draw inspections, hiring a contractor unfamiliar with the program, allowing scope creep mid-project, and not budgeting a contingency reserve are the most frequent issues.
Q: Why does choosing the right 203k general contractor matter so much?
A: An experienced contractor keeps draws, inspections, and construction moving together. An inexperienced one can stall a project for weeks over paperwork issues that are entirely avoidable.
A 203(k) loan can turn a home other buyers pass on into exactly the house you actually want, but only if the renovation side of the process runs as smoothly as the financing side. That’s almost entirely a function of who you hire, not luck.
Precision Remodeling has guided Memphis and Germantown homeowners through the FHA 203(k) process for over a decade, working directly with lenders and consultants so your draws, inspections, and construction timeline actually stay in sync. One experienced team, from the first specification to the final inspection.
Considering a 203(k) renovation loan? Call 901-258-2517 or schedule a free project consultation today. We’ll walk you through exactly what your loan type requires, before you’re already locked into a timeline.